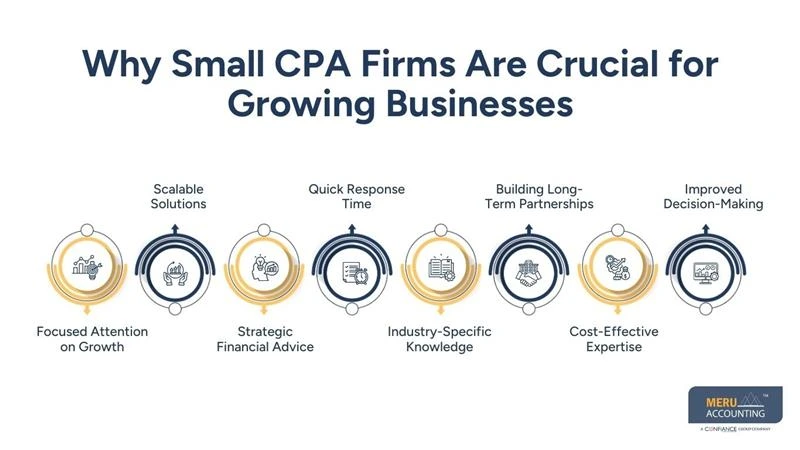
Why Small Businesses Trust CPAs During Major Transactions
You can feel a major transaction coming long before the papers are signed. Maybe you are buying out a partner, selling equipment, taking on debt, purchasing another business, or preparing to sell your own. The numbers start to matter in a different way, which is why many owners turn to small business accountants in Westwood. A decision that looked simple on the surface suddenly touches taxes, cash flow, payroll, valuation, and the story your books tell to lenders or buyers. That is usually the moment small business owners stop trying to hold everything in their heads.
This is why small business owners rely on CPAs for major transactions. Not because they want more paperwork, but because one wrong number can change the price, the tax bill, or the deal itself. A CPA helps you see what the transaction is really worth, what it will cost after tax, and what needs to be fixed before someone else finds it first.
Major transactions expose weak spots in your books
A big transaction puts pressure on every part of your financial records. If revenue has been categorized loosely, if personal and business expenses have mixed together, or if depreciation has not been tracked correctly, those issues come to the surface fast. What felt manageable during regular operations can become expensive when a buyer, lender, or IRS rule enters the picture.
You may already know this feeling. The business is doing well, yet the financials do not fully match the reality you live every day. Inventory counts are a little behind. Fixed assets were purchased over several years and no one is fully sure how each item was treated for tax purposes. A partner wants a number for their share, and everyone starts using different math. Stress rises because the transaction is no longer just a business move. It becomes a test of whether your records can stand up to scrutiny.
That is where a CPA earns trust. In business transaction accounting, the job is not just entering figures into software. The job is identifying risk before it turns into a delay, a lower offer, or an avoidable tax problem.
Tax consequences often matter more than the headline price
A deal can look great until taxes change the outcome. Selling equipment, real estate, or other business property can trigger gain recognition, depreciation recapture, or other tax treatment that cuts into proceeds. The IRS rules around property sales are not something most owners want to decode during a negotiation. The guidance in IRS Publication 544 on sales and other dispositions of assets shows how quickly tax treatment can become technical.
Even a transaction that seems routine can carry hidden cost. If you sell assets instead of stock, the buyer and seller may each prefer a different structure. If you bring in a new partner, basis and capital accounts matter. If you borrow to finance an acquisition, the debt service affects working capital right away. A CPA looks past the headline number and asks the harder question. What do you actually keep after taxes, fees, and timing issues are factored in?
That focus protects more than your return. It also helps you negotiate from a stronger position, because you understand the real economics of the deal instead of reacting after documents are drafted.
Small business accounting and tax work supports cleaner negotiations
Trust grows when the process gets clearer. During a major transaction, a CPA can organize financial statements, review prior returns, reconcile accounts, flag unusual expenses, and prepare schedules that explain the numbers. That gives buyers, lenders, attorneys, and partners fewer reasons to stall.
Clean records do something else that owners often underestimate. They lower emotion. When everyone is relying on the same set of verified numbers, there is less room for suspicion, inflated expectations, or last minute conflict. This is one reason CPA support during business sales and acquisitions matters so much. It creates a common financial language when the stakes are high.
If you need broader business guidance alongside the numbers, the SBA business counseling resources can also help you prepare for decisions that affect operations, funding, and planning.
DIY records and CPA guidance lead to very different outcomes
| Area | DIY Approach | CPA Guided Approach |
|---|---|---|
| Valuation support | Often based on rough revenue multiples or owner assumptions | Grounded in financial statements, adjustments, and tax impact |
| Tax treatment | May overlook gain, recapture, basis, or structure issues | Reviews likely tax results before terms are finalized |
| Due diligence readiness | Missing documents and unreconciled accounts can delay closing | Books, returns, and support are organized for review |
| Negotiation strength | Decisions made from top line numbers only | Decisions made from net outcome and cash flow reality |
| Post deal cleanup | Higher chance of amended filings or disputes | Cleaner transition with fewer surprises after closing |
For many owners, the real value is not only accuracy. It is timing. Fixing accounting issues before a deal closes is usually manageable. Fixing them after money has changed hands is harder, more expensive, and sometimes impossible.
The IRS also offers a useful baseline in Publication 334 for small business tax guidance, especially for owners trying to understand the rules that shape everyday reporting before a transaction puts those records under a microscope.
Three steps help you prepare before the pressure builds
Pull your last three years of financial and tax records. Gather returns, profit and loss statements, balance sheets, payroll reports, loan documents, and fixed asset details. If anything is missing or inconsistent, you want to know now, not when the other side asks for it.
Separate the deal price from the tax result. A high sale price can still produce a disappointing net result. Review how the transaction may be structured and how that structure affects taxes, cash flow, and timing.
Get your books reviewed before negotiations harden. Once terms are emotionally locked in, owners resist changing course even when the numbers say they should. Early review gives you room to adjust price, structure, or expectations without scrambling.
Trusted CPA guidance reduces risk when the stakes are personal
Major transactions are rarely just financial events. They touch your years of work, your family income, and your next move. That is why owners put so much trust in a CPA during these moments. Good accounting and tax guidance gives you a clearer view of value, a stronger handle on risk, and a better chance of closing the deal you think you are making.
If a major transaction is on the horizon, get your numbers reviewed before the pressure builds. Strong small business accounting and tax support can protect the deal and your peace of mind.

Post Comment